
How to know if your health insurance coverage is enough for your age
By Sarbvir Singh, Joint Group CEO, PB Fintech
Is having health insurance the same as having enough health insurance? Not always. Some buy in their 20s, while others might realise its importance after a hospitalisation well into their 30s. But one question that looms large for every consumer is - how much health insurance is enough. The answer is - there isn’t a single universal magic number that’s fit for everyone. Just like our life stages, health insurance needs do not remain static for a lifetime.
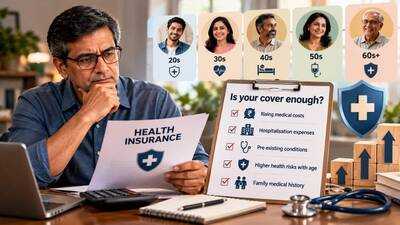
A health insurance policy can be perfectly adequate on the day you buy it and inadequate a few years later. The reason? Our financial lives change faster than our insurance cover often does. What makes the difference is not age alone, but what that person is trying to protect. The mistake is to treat the sum insured as a number that can be chosen once and forgotten. Here’s how health insurance coverage for different stages should ideally look like:
What determines how much health insurance you need?Age is a useful starting point, but adequate health cover is determined by a combination of healthcare costs, family circumstances and the terms of the policy itself. Five factors deserve particular attention are -
1. Age and life stage
Health insurance needs rarely remain the same throughout life. A young professional may initially need individual cover, but marriage, children and ageing parents can change both the number of people who need protection and the financial exposure involved. In one's 40s, for instance, a hospitalisation may coincide with home loan repayments, children's education expenses and responsibility for parents. As healthcare needs change with age, the existing sum insured should be reviewed rather than assumed to be sufficient simply because it was adequate when first purchased.
2. Where you live
The same medical procedure can cost very different amounts depending on the city and hospital. If you stay in a metro city like Mumbai, Delhi or Bangalore, the treatment cost will be inclusive of higher room rent, consultation fee, procedure and medicine costs as compared to a Tier 2 city. This does not mean everyone living in a metro city needs the highest available cover. It means the sum insured should be assessed against the cost of treatment at the hospitals one is likely to use. A useful starting point is to examine the cost of common major hospitalisations in your city and consider whether your cover can absorb the expense of common procedures comfortably.
3. Individual cover or family floater?
The answer to this question also changes with your life stage and evolving needs. The distinction between an individual policy and a family floater can determine how much protection each member actually has. If a Rs 15 lakh family floater is shared by four members, it is a common pool and not Rs 15 lakh of dedicated cover for each person. If one member undergoes a major surgery, the remaining cover available to others reduces accordingly, subject to the policy’s benefits. A floater may work well for a young family with relatively similar healthcare needs, while individual policies may be worth considering when members are older or have different medical requirements. The decision should account for the family’s age profile, health history and the possibility of multiple claims in the same year.
4. Pre-existing diseases and waiting periods
Urban India is seeing a rapid rise of lifestyle diseases, even among the young and healthy. So, factoring in pre-existing diseases and the waiting periods attached to them is important. In this regard, a higher sum insured does not automatically mean every medical expense will be covered from day one. Conditions such as diabetes, hypertension or thyroid disorders may be subject to specified waiting periods, depending on the policy.
Consumers should disclose their medical history accurately and check when treatment related to a pre-existing condition becomes eligible for coverage. Buying insurance earlier, before such conditions develop, can help avoid some of these restrictions. For those who already have a diagnosis, there are plans available that waive off the waiting period for a small amount of additional premium.
5. The policy’s actual coverage, not just its sum insured
Here’s what most policyholders don’t understand - having a Rs 10 lakh policy does not necessarily mean getting the entire amount of an admissible Rs 10 lakh hospital bill. Why? Because copayment, voluntary deductible, room-rent cap and disease-specific sub-limits can leave the policyholder bearing the part of the cost. For example, a policy with a 20% copayment would require the insured to bear Rs 2 lakh of a Rs 10 lakh admissible claim, before accounting for any other applicable restrictions. Consumers should therefore examine the policy’s conditions alongside the headline cover amount. Employer-provided insurance should also be assessed in this context, particularly if it is the family’s only protection or may cease when employment ends.
In a nutshell, assess your age and life-stage. But the objective is not to buy the largest policy available or chase a particular number. The purpose of the policy is to cover is adequate for the medical costs you could face and that its terms do not leave you with an unexpected financial burden. A review of these factors becomes especially important at major life transitions, when both healthcare needs and financial responsibilities can change.
(Disclaimer: Recommendations and views on the stock market, or any other asset classes or personal finance management tips given by experts and analysts are their own. These opinions do not represent the views of The Times of India.)
Is having health insurance the same as having enough health insurance? Not always. Some buy in their 20s, while others might realise its importance after a hospitalisation well into their 30s. But one question that looms large for every consumer is - how much health insurance is enough. The answer is - there isn’t a single universal magic number that’s fit for everyone. Just like our life stages, health insurance needs do not remain static for a lifetime.
A health insurance policy can be perfectly adequate on the day you buy it and inadequate a few years later. The reason? Our financial lives change faster than our insurance cover often does. What makes the difference is not age alone, but what that person is trying to protect. The mistake is to treat the sum insured as a number that can be chosen once and forgotten. Here’s how health insurance coverage for different stages should ideally look like:
What determines how much health insurance you need?Age is a useful starting point, but adequate health cover is determined by a combination of healthcare costs, family circumstances and the terms of the policy itself. Five factors deserve particular attention are -
1. Age and life stage
Health insurance needs rarely remain the same throughout life. A young professional may initially need individual cover, but marriage, children and ageing parents can change both the number of people who need protection and the financial exposure involved. In one's 40s, for instance, a hospitalisation may coincide with home loan repayments, children's education expenses and responsibility for parents. As healthcare needs change with age, the existing sum insured should be reviewed rather than assumed to be sufficient simply because it was adequate when first purchased.
2. Where you live
The same medical procedure can cost very different amounts depending on the city and hospital. If you stay in a metro city like Mumbai, Delhi or Bangalore, the treatment cost will be inclusive of higher room rent, consultation fee, procedure and medicine costs as compared to a Tier 2 city. This does not mean everyone living in a metro city needs the highest available cover. It means the sum insured should be assessed against the cost of treatment at the hospitals one is likely to use. A useful starting point is to examine the cost of common major hospitalisations in your city and consider whether your cover can absorb the expense of common procedures comfortably.
3. Individual cover or family floater?
The answer to this question also changes with your life stage and evolving needs. The distinction between an individual policy and a family floater can determine how much protection each member actually has. If a Rs 15 lakh family floater is shared by four members, it is a common pool and not Rs 15 lakh of dedicated cover for each person. If one member undergoes a major surgery, the remaining cover available to others reduces accordingly, subject to the policy’s benefits. A floater may work well for a young family with relatively similar healthcare needs, while individual policies may be worth considering when members are older or have different medical requirements. The decision should account for the family’s age profile, health history and the possibility of multiple claims in the same year.
4. Pre-existing diseases and waiting periods
Urban India is seeing a rapid rise of lifestyle diseases, even among the young and healthy. So, factoring in pre-existing diseases and the waiting periods attached to them is important. In this regard, a higher sum insured does not automatically mean every medical expense will be covered from day one. Conditions such as diabetes, hypertension or thyroid disorders may be subject to specified waiting periods, depending on the policy.
Consumers should disclose their medical history accurately and check when treatment related to a pre-existing condition becomes eligible for coverage. Buying insurance earlier, before such conditions develop, can help avoid some of these restrictions. For those who already have a diagnosis, there are plans available that waive off the waiting period for a small amount of additional premium.
5. The policy’s actual coverage, not just its sum insured
Here’s what most policyholders don’t understand - having a Rs 10 lakh policy does not necessarily mean getting the entire amount of an admissible Rs 10 lakh hospital bill. Why? Because copayment, voluntary deductible, room-rent cap and disease-specific sub-limits can leave the policyholder bearing the part of the cost. For example, a policy with a 20% copayment would require the insured to bear Rs 2 lakh of a Rs 10 lakh admissible claim, before accounting for any other applicable restrictions. Consumers should therefore examine the policy’s conditions alongside the headline cover amount. Employer-provided insurance should also be assessed in this context, particularly if it is the family’s only protection or may cease when employment ends.
In a nutshell, assess your age and life-stage. But the objective is not to buy the largest policy available or chase a particular number. The purpose of the policy is to cover is adequate for the medical costs you could face and that its terms do not leave you with an unexpected financial burden. A review of these factors becomes especially important at major life transitions, when both healthcare needs and financial responsibilities can change.
(Disclaimer: Recommendations and views on the stock market, or any other asset classes or personal finance management tips given by experts and analysts are their own. These opinions do not represent the views of The Times of India.)
Next Story