Post-Diwali Money Reset: 5 Essential Financial Changes to Make Before Welcoming 2027

Festive celebrations can bring additional expenses that affect household savings and monthly budgets. Once the shopping, travel and family gatherings are over, reviewing these financial commitments can help prevent temporary spending from becoming a longer-term burden.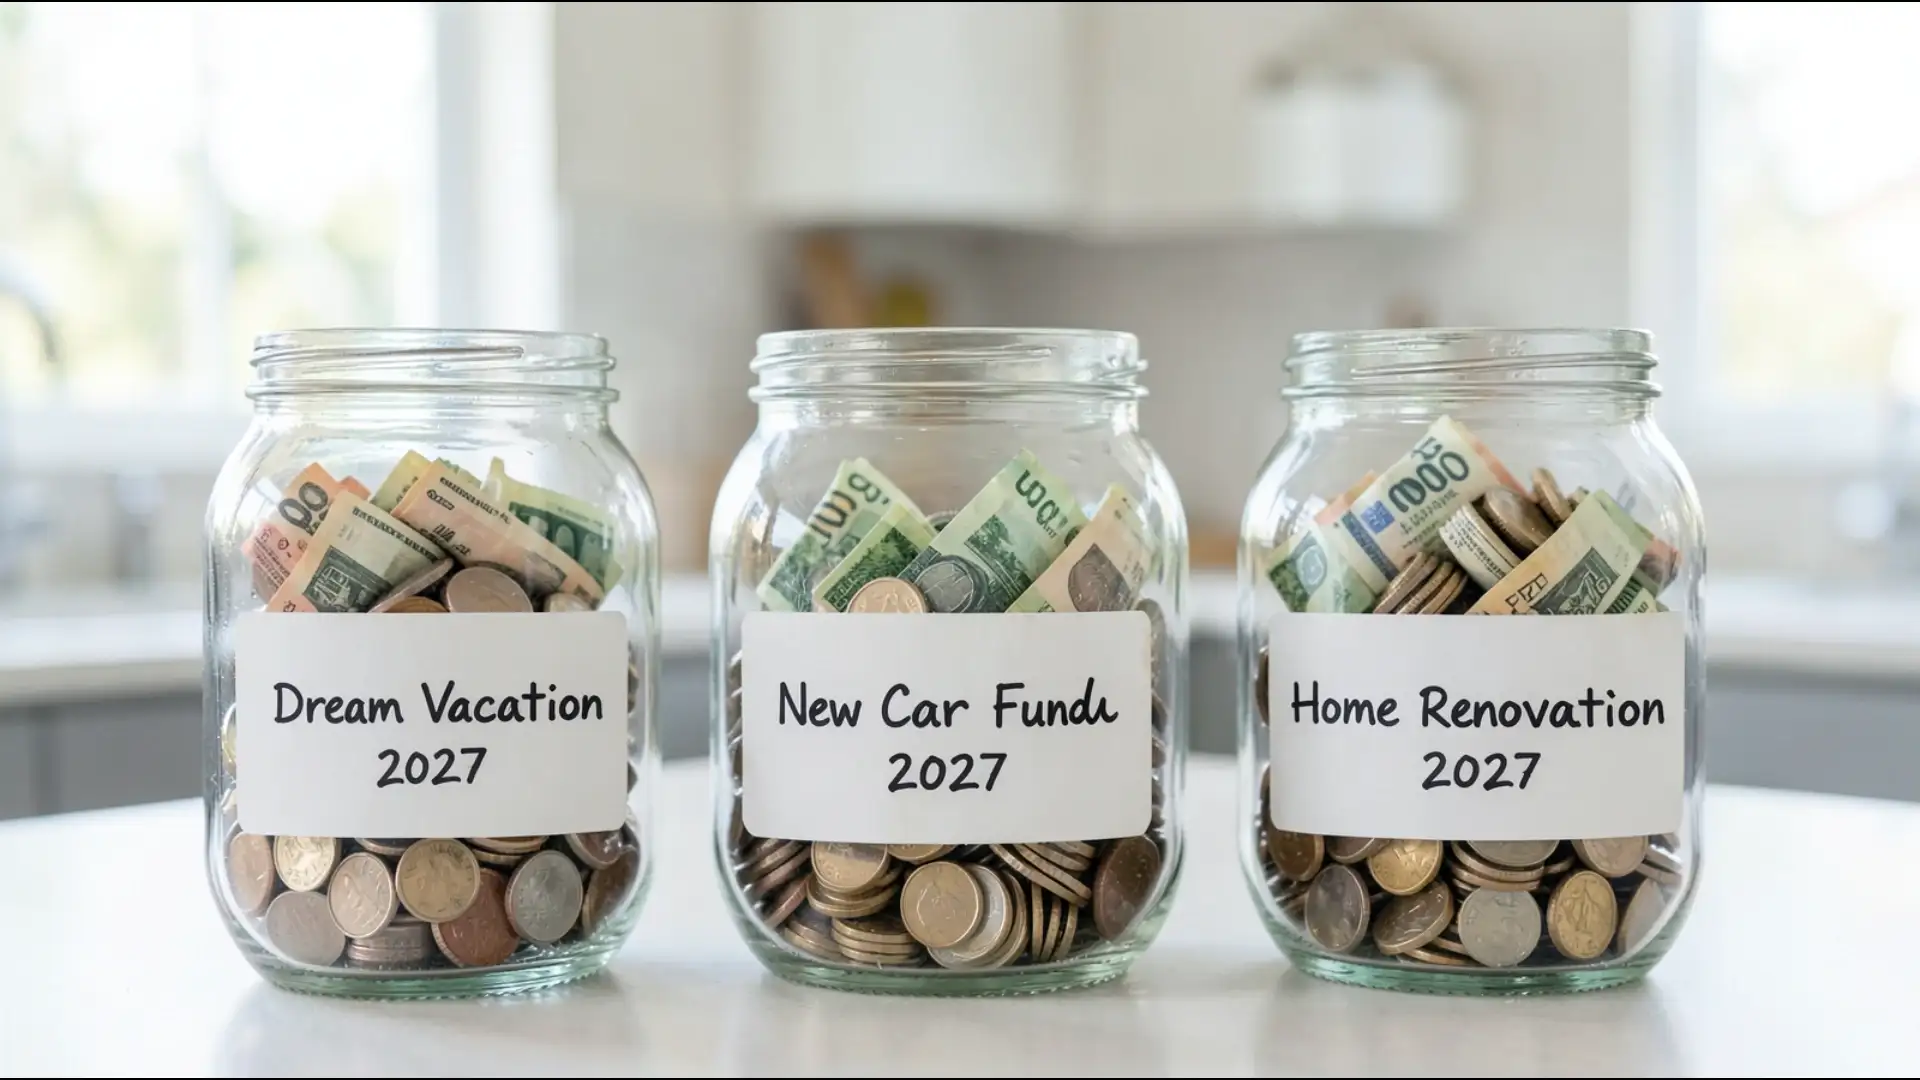
With 2027 approaching, November offers an opportunity to reassess money habits and prepare for upcoming responsibilities. A few practical adjustments can improve financial discipline without requiring complicated investment decisions or drastic lifestyle changes.
Start by checking recent bank statements, credit card bills and digital payment records. Compare the actual expenditure with your usual monthly budget to identify where additional money was spent.
Pay particular attention to purchases made using credit cards or EMI facilities. Although these payment methods can spread expenses over several months, they also create future financial commitments that need to be included in your budget.
Next, list your regular income and essential monthly expenses, including rent, groceries, utility bills, transport, education costs and loan repayments.
The difference between your income and unavoidable expenditure will indicate how much money is available for savings and other financial goals.
According to financial planning experts, a realistic budget should reflect actual spending patterns rather than an ideal figure that is difficult to maintain.
As 2027 approaches, use this assessment to establish monthly spending limits and identify categories where unnecessary expenditure can be reduced.
A sudden medical requirement, job loss, urgent home repair or temporary reduction in earnings can create pressure on savings. Without an accessible reserve, families may have to depend on credit cards or personal loans to manage these situations.
A commonly recommended target is to maintain emergency savings equivalent to three to six months of essential household expenses.
For example, if your necessary monthly expenditure is Rs 35,000, a reserve of Rs 1.05 lakh to Rs 2.10 lakh would cover three to six months.
The amount may need to be higher for households with irregular income, multiple dependants or substantial financial commitments.
Keep this money in accessible financial instruments, such as a savings account or suitable liquid options, rather than locking it into investments with withdrawal restrictions.
It is also important to maintain a clear distinction between emergency savings and money reserved for planned purchases.
Using this reserve for holidays, festive shopping or expensive gadgets can leave the household financially exposed when a genuine emergency arises.
Credit card balances and certain personal loans can carry relatively high interest rates. Continuing to pay only the minimum amount due on a credit card may keep the outstanding balance active for an extended period and increase the total repayment cost.
Prepare a list of all existing borrowings, including outstanding amounts, interest rates, monthly instalments and repayment deadlines.
If you have several debts, prioritise those carrying the highest interest rates while maintaining the required payments on other obligations.
This approach can help reduce the overall interest burden over time.
For example, clearing an expensive credit card balance may free up money that would otherwise go towards interest payments. That amount can subsequently be redirected towards emergency savings or long-term investments.
However, avoid using your entire savings reserve to repay debt. Maintaining some financial protection against unexpected expenses remains important.
Borrowers can also examine whether their existing loan terms are competitive and whether refinancing or part-prepayment could offer meaningful savings after accounting for applicable charges.
Review your holdings across mutual funds, shares, fixed deposits and other investment products.
Consider whether the balance between equity and debt investments remains appropriate for your investment horizon, financial responsibilities and ability to tolerate market fluctuations.
For instance, someone saving for retirement several decades away may have different investment requirements from a person planning to purchase a house within the next two years.
Changes in income, family responsibilities and financial goals can also affect how much investment risk an individual is comfortable taking.
Portfolio rebalancing may be worth considering if the allocation between different asset categories has moved significantly away from the intended level.
However, investors should avoid making sudden decisions based entirely on short-term market movements or recent returns.
According to investment experts, a portfolio should be assessed in the context of long-term goals, diversification and risk tolerance rather than performance over a few weeks or months.
Reviewing investments regularly can help identify whether existing contributions need adjustment and whether any financial goals require a different approach.
Think about the major expenses you may face during 2027. These could include purchasing a vehicle, renovating your home, funding higher education, planning a family holiday or making a down payment on property.
Estimate the likely cost of each goal and identify when the payment will be required.
Once the amount and timeframe are clear, calculate how much needs to be saved every month.
For example, someone planning a purchase worth Rs 2.4 lakh after 12 months would need to accumulate an average of Rs 20,000 every month, assuming no investment returns.
If that amount is beyond the available budget, consider adjusting the purchase timeline or setting a more affordable target.
Avoid relying on credit cards or personal loans for expenses that could have been anticipated and funded through regular savings.
It is also useful to separate short-term financial goals from longer-term priorities such as retirement and children's education. Each requires a suitable savings and investment approach.
Discussing major financial decisions with family members can help establish shared priorities and prevent conflicting spending plans.
Begin by understanding festive expenditure, setting a practical budget and ensuring that expensive debt does not continue consuming a large share of monthly income.
Building an emergency reserve and reviewing existing investments can provide additional financial stability, while clearly defined targets can give your savings a specific purpose.
It is equally important to revisit the plan regularly. Changes in income, household responsibilities and unexpected expenses may require adjustments during the year.
A structured approach to budgeting and saving can help families enter 2027 with better financial control and a clearer direction towards their long-term goals.
Disclaimer: This article is intended for informational purposes only and should not be considered financial or investment advice. Financial circumstances, investment risks and individual requirements vary. Readers should assess their financial position and consult a qualified financial adviser before making investment or borrowing decisions.
With 2027 approaching, November offers an opportunity to reassess money habits and prepare for upcoming responsibilities. A few practical adjustments can improve financial discipline without requiring complicated investment decisions or drastic lifestyle changes.
1. Recalculate Your Household Budget After Diwali
Before setting new savings targets, understand how the festive season has affected your finances. Shopping, gifts, decorations, travel and celebrations can collectively consume a considerable portion of household income.Start by checking recent bank statements, credit card bills and digital payment records. Compare the actual expenditure with your usual monthly budget to identify where additional money was spent.
Pay particular attention to purchases made using credit cards or EMI facilities. Although these payment methods can spread expenses over several months, they also create future financial commitments that need to be included in your budget.
Next, list your regular income and essential monthly expenses, including rent, groceries, utility bills, transport, education costs and loan repayments.
The difference between your income and unavoidable expenditure will indicate how much money is available for savings and other financial goals.
According to financial planning experts, a realistic budget should reflect actual spending patterns rather than an ideal figure that is difficult to maintain.
As 2027 approaches, use this assessment to establish monthly spending limits and identify categories where unnecessary expenditure can be reduced.
2. Strengthen Your Emergency Fund Before Making New Investments
An emergency fund provides financial support when unexpected situations disrupt regular income or increase household expenses.A sudden medical requirement, job loss, urgent home repair or temporary reduction in earnings can create pressure on savings. Without an accessible reserve, families may have to depend on credit cards or personal loans to manage these situations.
A commonly recommended target is to maintain emergency savings equivalent to three to six months of essential household expenses.
For example, if your necessary monthly expenditure is Rs 35,000, a reserve of Rs 1.05 lakh to Rs 2.10 lakh would cover three to six months.
The amount may need to be higher for households with irregular income, multiple dependants or substantial financial commitments.
Keep this money in accessible financial instruments, such as a savings account or suitable liquid options, rather than locking it into investments with withdrawal restrictions.
It is also important to maintain a clear distinction between emergency savings and money reserved for planned purchases.
Using this reserve for holidays, festive shopping or expensive gadgets can leave the household financially exposed when a genuine emergency arises.
3. Prioritise High-Interest Debt Repayment
Outstanding debt can become a major obstacle to improving financial stability, particularly when interest charges accumulate faster than savings grow.Credit card balances and certain personal loans can carry relatively high interest rates. Continuing to pay only the minimum amount due on a credit card may keep the outstanding balance active for an extended period and increase the total repayment cost.
Prepare a list of all existing borrowings, including outstanding amounts, interest rates, monthly instalments and repayment deadlines.
If you have several debts, prioritise those carrying the highest interest rates while maintaining the required payments on other obligations.
This approach can help reduce the overall interest burden over time.
For example, clearing an expensive credit card balance may free up money that would otherwise go towards interest payments. That amount can subsequently be redirected towards emergency savings or long-term investments.
However, avoid using your entire savings reserve to repay debt. Maintaining some financial protection against unexpected expenses remains important.
Borrowers can also examine whether their existing loan terms are competitive and whether refinancing or part-prepayment could offer meaningful savings after accounting for applicable charges.
4. Review Your Investment Portfolio Before Increasing Contributions
A new financial year or calendar year is not necessarily a reason to make major changes to existing investments. However, it can be a useful opportunity to check whether your portfolio still reflects your financial objectives.Review your holdings across mutual funds, shares, fixed deposits and other investment products.
Consider whether the balance between equity and debt investments remains appropriate for your investment horizon, financial responsibilities and ability to tolerate market fluctuations.
For instance, someone saving for retirement several decades away may have different investment requirements from a person planning to purchase a house within the next two years.
Changes in income, family responsibilities and financial goals can also affect how much investment risk an individual is comfortable taking.
Portfolio rebalancing may be worth considering if the allocation between different asset categories has moved significantly away from the intended level.
However, investors should avoid making sudden decisions based entirely on short-term market movements or recent returns.
According to investment experts, a portfolio should be assessed in the context of long-term goals, diversification and risk tolerance rather than performance over a few weeks or months.
Reviewing investments regularly can help identify whether existing contributions need adjustment and whether any financial goals require a different approach.
5. Set Clear Financial Targets for 2027
A savings plan becomes easier to follow when money is being set aside for specific purposes.Think about the major expenses you may face during 2027. These could include purchasing a vehicle, renovating your home, funding higher education, planning a family holiday or making a down payment on property.
Estimate the likely cost of each goal and identify when the payment will be required.
Once the amount and timeframe are clear, calculate how much needs to be saved every month.
For example, someone planning a purchase worth Rs 2.4 lakh after 12 months would need to accumulate an average of Rs 20,000 every month, assuming no investment returns.
You may also like
- DLF to invest Rs 3,750 cr in JV with Everstone to buy stake in IREO India
- 8th Pay Commission Update: When Will New Salary and Pension Revisions Be Implemented? Check Expected Timeline
- Explained: Why Nvidia shares dropped 4% in overnight trade
- PM Kisan Yojana: Know how many days you will have to wait for the 25th installment; you will get good news soon.
- Gold price prediction today: Will gold prices face upside resistance? Check outlook for November 9, 2026 week
If that amount is beyond the available budget, consider adjusting the purchase timeline or setting a more affordable target.
Avoid relying on credit cards or personal loans for expenses that could have been anticipated and funded through regular savings.
It is also useful to separate short-term financial goals from longer-term priorities such as retirement and children's education. Each requires a suitable savings and investment approach.
Discussing major financial decisions with family members can help establish shared priorities and prevent conflicting spending plans.
Make Financial Discipline a Year-Round Habit
Improving your financial position does not depend on making several drastic changes immediately after Diwali. Small adjustments, followed consistently, can have a meaningful impact on household money management.Begin by understanding festive expenditure, setting a practical budget and ensuring that expensive debt does not continue consuming a large share of monthly income.
Building an emergency reserve and reviewing existing investments can provide additional financial stability, while clearly defined targets can give your savings a specific purpose.
It is equally important to revisit the plan regularly. Changes in income, household responsibilities and unexpected expenses may require adjustments during the year.
A structured approach to budgeting and saving can help families enter 2027 with better financial control and a clearer direction towards their long-term goals.
Disclaimer: This article is intended for informational purposes only and should not be considered financial or investment advice. Financial circumstances, investment risks and individual requirements vary. Readers should assess their financial position and consult a qualified financial adviser before making investment or borrowing decisions.
Loving Newspoint? Download the app now