
KVP Scheme: Invest Money in This Post Office Scheme and Get Double the Amount After a Fixed Period
If you are looking for a government-backed savings option for long-term investment, the Post Office Kisan Vikas Patra (KVP) scheme can be considered. Despite its name, the scheme is not restricted to farmers. It allows individuals to make a one-time investment and grow their savings over a fixed period.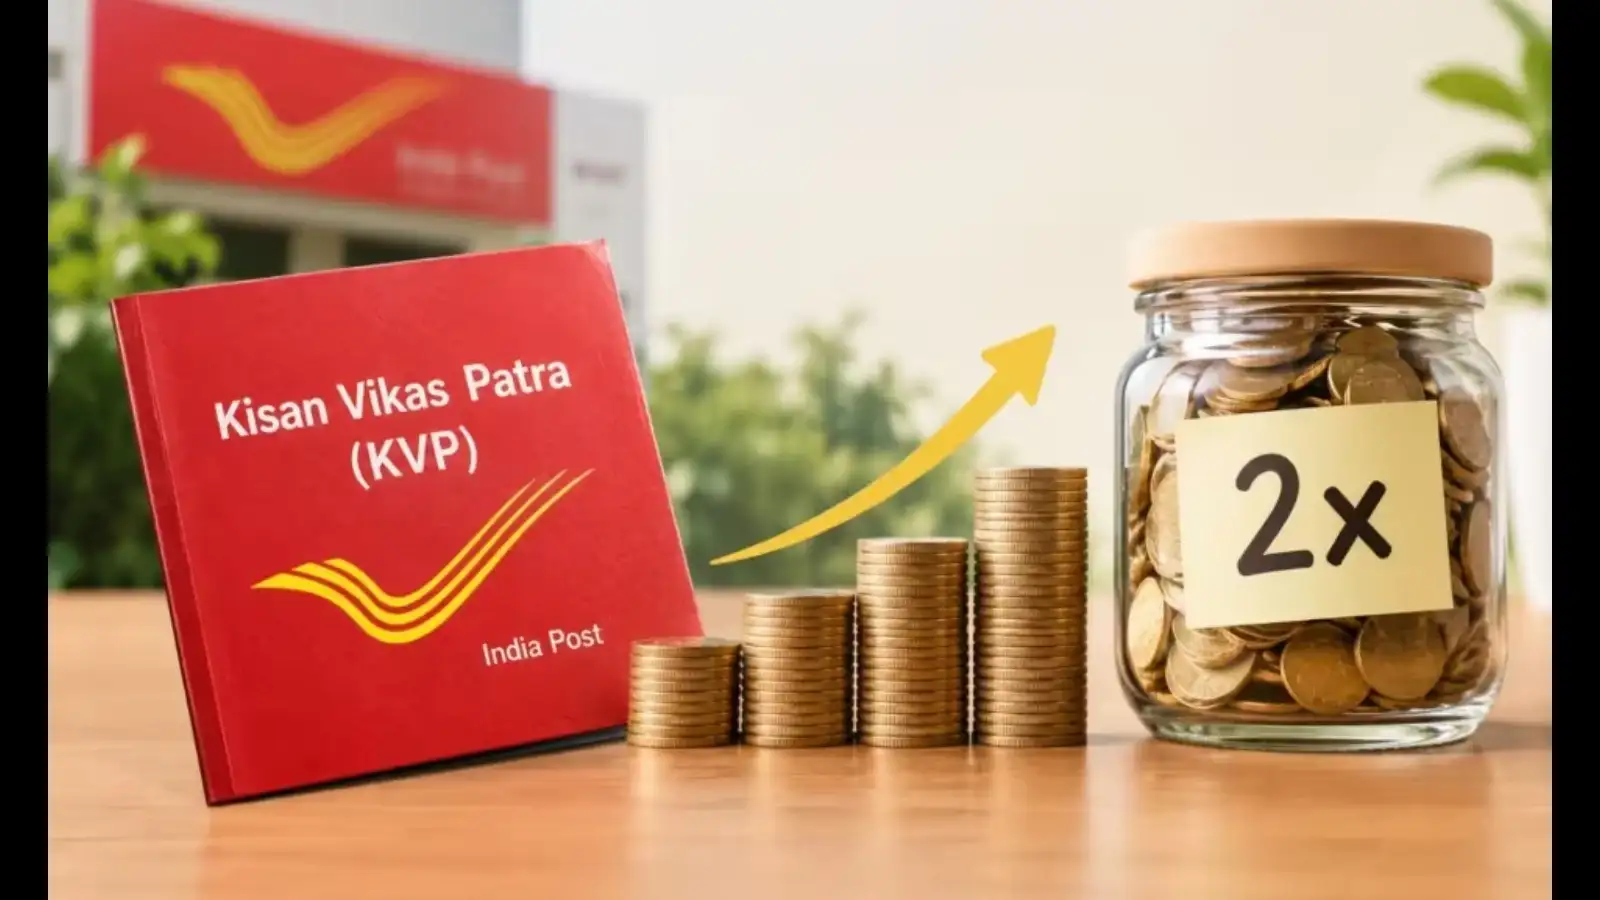
One of the main features of KVP is that the investment doubles at maturity, subject to the applicable interest rate and tenure. This makes it a potential option for people looking for a predictable long-term savings instrument.
For example, an investment of ₹1 lakh would grow to ₹2 lakh at maturity, based on the stated maturity period and applicable rate.
Since KVP involves a one-time deposit, investors do not need to make regular monthly contributions. They can invest a lump sum and keep it invested until maturity.
After completing the minimum period, premature withdrawal may be possible as per the applicable rules. However, withdrawing early means the investment will not remain invested for the full period required for it to double.
Before investing, it is important to check the latest interest rate, maturity rules and withdrawal conditions, as small savings scheme rates and rules can change.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Please consult a certified financial advisor before making any decisions. NewsPoint is not responsible for any gains or losses arising from this information.
What Is Kisan Vikas Patra?
Kisan Vikas Patra is a small savings scheme offered through post offices. An individual can invest a lump sum amount and keep it in the scheme for the prescribed maturity period.One of the main features of KVP is that the investment doubles at maturity, subject to the applicable interest rate and tenure. This makes it a potential option for people looking for a predictable long-term savings instrument.
Kisan Vikas Patra Interest Rate
The KVP scheme currently offers an interest rate of7.5% per annum. At this rate, an investment takes 115 months, or 9 years and 7 months, to double.For example, an investment of ₹1 lakh would grow to ₹2 lakh at maturity, based on the stated maturity period and applicable rate.
Minimum Investment And Maximum Limit
Investors can start with a minimum investment of ₹1,000. There is no maximum investment limit under the scheme.Since KVP involves a one-time deposit, investors do not need to make regular monthly contributions. They can invest a lump sum and keep it invested until maturity.
When Can You Withdraw Money?
Kisan Vikas Patra comes with a minimum lock-in period of 2 years and 6 months. The investment generally cannot be withdrawn before this period, except under specified conditions.After completing the minimum period, premature withdrawal may be possible as per the applicable rules. However, withdrawing early means the investment will not remain invested for the full period required for it to double.
Who Can Consider KVP?
KVP may suit investors who want to keep a lump sum amount in a government-backed small savings scheme for the long term. It can also be considered by those who prefer a fixed-tenure investment instead of market-linked options.Before investing, it is important to check the latest interest rate, maturity rules and withdrawal conditions, as small savings scheme rates and rules can change.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Please consult a certified financial advisor before making any decisions. NewsPoint is not responsible for any gains or losses arising from this information.
Next Story