
NBFCs redesign lending models ahead of revolving credit curbs


Mumbai: Non-banking financial companies (NBFCs) are developing alternative loan products to replace revolving credit facilities ahead of the Reserve Bank of India's proposed restrictions, seeking to protect lending volumes and retain customers while moving towards term-loan structures.
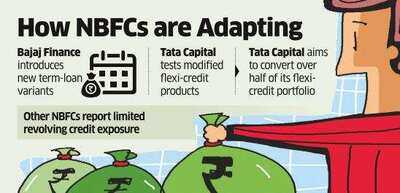
Bajaj Finance has introduced new term-loan variants, while Tata Capital has begun piloting modified flexi-loan products and plans further trials this month.
The RBI's August draft proposes that NBFCs, except authorised credit card issuers, offer only term loans. These may be disbursed in instalments but must follow a predetermined repayment schedule; the repaid principal cannot replenish the sanctioned limit. Revolving facilities, by contrast, let borrowers draw, repay and borrow again within an approved limit, an arrangement particularly useful for working capital needs.
 "We are already launching a set of different variants of term loans on November 1st which do not allow withdrawal," Rajeev Jain, vice chairman and managing director of Bajaj Finance, said during its October 19 earnings call.
Jain said a complete ban could temporarily affect assets under management and cause a marginal compression in net interest margins and profitability. However, the company is preparing alternatives rather than waiting for the RBI's final decision.
Tata Capital expects to convert more than half of its flexi-credit portfolio into modified products without a revolving facility. Managing director and CEO Rajiv Sabharwal said the company had already tested some alternatives and would begin testing the remaining variants in early November.
"Our modified products are almost at a similar price like the flexi loans," Sabharwal said during the October 27 earnings call. He added that existing flexi loans carry higher interest rates than ordinary term loans.
Flexi loans account for about 2-2.5% of Tata Capital's book. Sabharwal said roughly 90% of this business serves micro, small and medium enterprises (MSMEs). Tata Capital has not reduced its revolving-credit exposure while awaiting the final rules.
Other NBFCs, including Aditya Birla Capital, Cholamandalam Investment and Finance Company and Shriram Finance, have indicated limited exposure to revolving credit products.
Aditya Birla Capital's NBFC chief Rakesh Singh said its exposure was very small and primarily concentrated in supply-chain financing and loans against shares. Cholamandalam's chief financial officer D Arul Selvan said revolving credit facilities accounted for just 0.6-0.7% of its loan book, or about ₹1,600 crore, largely comprising flexi-personal loans. Shriram Finance executive vice chairman Umesh Revankar also indicated that its exposure was limited, primarily comprising dealer trade advances. He estimated outstanding revolving credit facilities across NBFCs at about ₹2 lakh crore, against a total loan book of roughly ₹30 lakh crore.
Bajaj Finance has introduced new term-loan variants, while Tata Capital has begun piloting modified flexi-loan products and plans further trials this month.
The RBI's August draft proposes that NBFCs, except authorised credit card issuers, offer only term loans. These may be disbursed in instalments but must follow a predetermined repayment schedule; the repaid principal cannot replenish the sanctioned limit. Revolving facilities, by contrast, let borrowers draw, repay and borrow again within an approved limit, an arrangement particularly useful for working capital needs.
Jain said a complete ban could temporarily affect assets under management and cause a marginal compression in net interest margins and profitability. However, the company is preparing alternatives rather than waiting for the RBI's final decision.
Tata Capital expects to convert more than half of its flexi-credit portfolio into modified products without a revolving facility. Managing director and CEO Rajiv Sabharwal said the company had already tested some alternatives and would begin testing the remaining variants in early November.
"Our modified products are almost at a similar price like the flexi loans," Sabharwal said during the October 27 earnings call. He added that existing flexi loans carry higher interest rates than ordinary term loans.
Flexi loans account for about 2-2.5% of Tata Capital's book. Sabharwal said roughly 90% of this business serves micro, small and medium enterprises (MSMEs). Tata Capital has not reduced its revolving-credit exposure while awaiting the final rules.
Other NBFCs, including Aditya Birla Capital, Cholamandalam Investment and Finance Company and Shriram Finance, have indicated limited exposure to revolving credit products.
Aditya Birla Capital's NBFC chief Rakesh Singh said its exposure was very small and primarily concentrated in supply-chain financing and loans against shares. Cholamandalam's chief financial officer D Arul Selvan said revolving credit facilities accounted for just 0.6-0.7% of its loan book, or about ₹1,600 crore, largely comprising flexi-personal loans. Shriram Finance executive vice chairman Umesh Revankar also indicated that its exposure was limited, primarily comprising dealer trade advances. He estimated outstanding revolving credit facilities across NBFCs at about ₹2 lakh crore, against a total loan book of roughly ₹30 lakh crore.
Next Story