
EPF and NPS: Can Salaried Employees Have Both for Retirement?
Planning for retirement does not necessarily mean choosing between EPF and NPS . Salaried employees who meet the applicable eligibility conditions can have both schemes at the same time. While EPF offers employment-linked retirement savings through regular contributions, NPS provides an additional market-linked investment option. Using both can help employees create a more diversified retirement corpus, provided they understand the contribution, tax and withdrawal rules.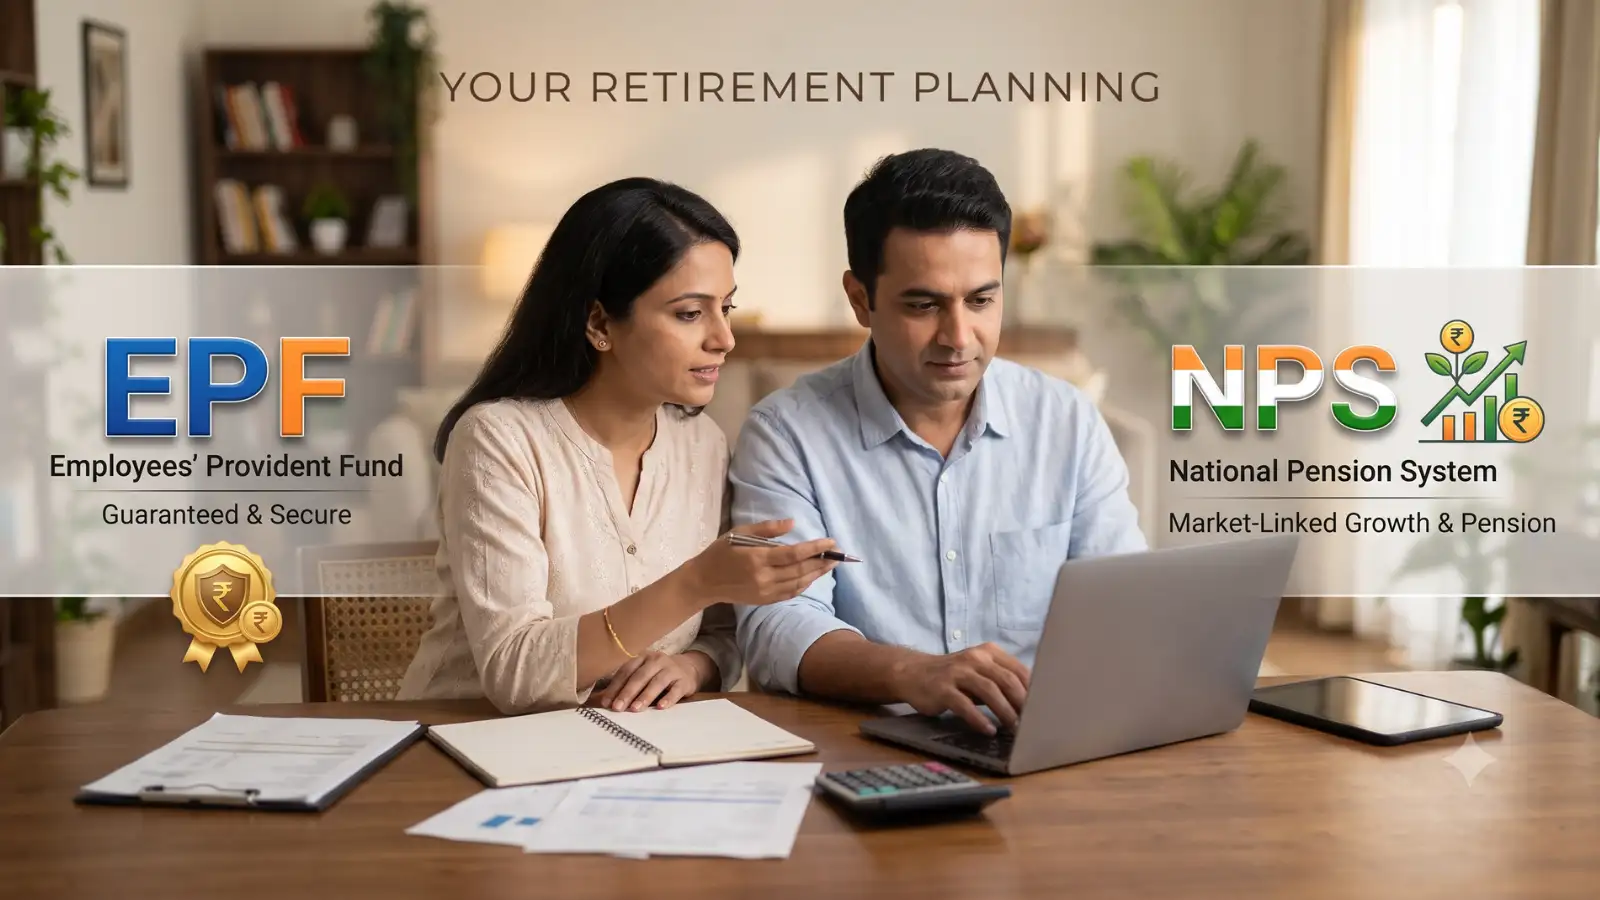
The two schemes operate differently. EPF is generally connected to salaried employment, with contributions made by the employee and employer under applicable rules. NPS is a defined-contribution pension system where the accumulated money is invested in market-linked assets.
This means eligible employees can use both schemes as separate components of their long-term retirement strategy.
A portion of the employer's contribution may go towards the Employees' Pension Scheme (EPS), subject to the applicable provisions.
Since EPF contributions are linked to employment and are made regularly, the scheme can provide a structured way to accumulate retirement savings over the course of a career.
The money contributed to NPS is invested in market-linked asset classes. Depending on the NPS model and the employer's policy, contributions may come from the employee, employer or both.
Unlike EPF, NPS gives subscribers investment choices across different asset classes. Since returns are linked to market performance, the value of the retirement corpus can fluctuate depending on investment performance.
Some organisations may offer NPS as an additional retirement benefit alongside EPF. Others may include NPS within their salary or benefits structure. Therefore, employees should check their company's NPS policy and salary structure before assuming that an employer contribution will be available under both schemes.
If your employer offers NPS contributions, understanding how these contributions are structured can help you make better use of the available retirement benefits.
However, tax treatment can vary depending on factors such as the type of contribution, withdrawals and the applicable tax rules.
Since tax provisions can change, employees should check the latest rules and applicable limits before making retirement-planning decisions.
EPF can provide regular, employment-linked savings, while NPS can add a market-linked investment component to the overall retirement portfolio. This can help diversify the way retirement savings are accumulated.
However, NPS also comes with specific rules governing withdrawals and exit. Since its returns depend on the performance of the underlying investments, employees should understand the associated risks and restrictions before investing.
Can You Have EPF And NPS Together?
Yes, employees can generally maintain both EPF and NPS accounts. Having an EPF account through your employer does not stop you from subscribing to the National Pension System.The two schemes operate differently. EPF is generally connected to salaried employment, with contributions made by the employee and employer under applicable rules. NPS is a defined-contribution pension system where the accumulated money is invested in market-linked assets.
This means eligible employees can use both schemes as separate components of their long-term retirement strategy.
How Does EPF Work?
The Employees' Provident Fund is designed to help salaried employees build retirement savings through regular contributions. Under the standard EPF structure, an employee contributes 12% of eligible wages, while the employer also makes a contribution as prescribed under the applicable rules.A portion of the employer's contribution may go towards the Employees' Pension Scheme (EPS), subject to the applicable provisions.
Since EPF contributions are linked to employment and are made regularly, the scheme can provide a structured way to accumulate retirement savings over the course of a career.
How Does NPS Work?
The National Pension System is a defined-contribution retirement scheme that allows subscribers to invest towards their long-term financial needs.The money contributed to NPS is invested in market-linked asset classes. Depending on the NPS model and the employer's policy, contributions may come from the employee, employer or both.
Unlike EPF, NPS gives subscribers investment choices across different asset classes. Since returns are linked to market performance, the value of the retirement corpus can fluctuate depending on investment performance.
Can Your Employer Contribute To Both EPF And NPS?
Whether an employer contributes to both schemes depends on the company's retirement-benefit structure.Some organisations may offer NPS as an additional retirement benefit alongside EPF. Others may include NPS within their salary or benefits structure. Therefore, employees should check their company's NPS policy and salary structure before assuming that an employer contribution will be available under both schemes.
If your employer offers NPS contributions, understanding how these contributions are structured can help you make better use of the available retirement benefits.
What Are The Tax Benefits Of EPF And NPS?
EPF and NPS are governed by different tax provisions. NPS may provide tax benefits for eligible contributions, including employer contributions under Section 80CCD(2), subject to the applicable limits and tax regime.However, tax treatment can vary depending on factors such as the type of contribution, withdrawals and the applicable tax rules.
Since tax provisions can change, employees should check the latest rules and applicable limits before making retirement-planning decisions.
Why Should You Consider Using Both EPF And NPS?
Using both schemes can give salaried employees two different avenues for building retirement savings.EPF can provide regular, employment-linked savings, while NPS can add a market-linked investment component to the overall retirement portfolio. This can help diversify the way retirement savings are accumulated.
However, NPS also comes with specific rules governing withdrawals and exit. Since its returns depend on the performance of the underlying investments, employees should understand the associated risks and restrictions before investing.
EPF Vs NPS : How Are They Different?
Although both are designed to support retirement planning , EPF and NPS have different structures.- EPF: Primarily linked to salaried employment and regular contributions through the employer.
- NPS: A defined-contribution pension system with market-linked investments.
- EPF contributions: Generally made by both employee and employer under applicable rules.
- NPS contributions: May be made by the employee, employer or both, depending on the applicable model.
- Investment choice: NPS offers investment choices across market-linked asset classes, while EPF follows its prescribed framework.
- Withdrawal rules: EPF and NPS have different rules for withdrawals and retirement benefits.
Next Story