Just Married? Master Your Finances With These Expert Tips

Marriage marks the beginning of a beautiful journey filled with shared dreams and aspirations. While love and companionship take centre stage, financial harmony plays a crucial supporting role. Proper financial planning can ensure a smooth transition into this new phase of life, helping couples manage their expenses, align their goals, and secure a stable future. Here's a practical guide for newlyweds to start their financial journey on the right foot.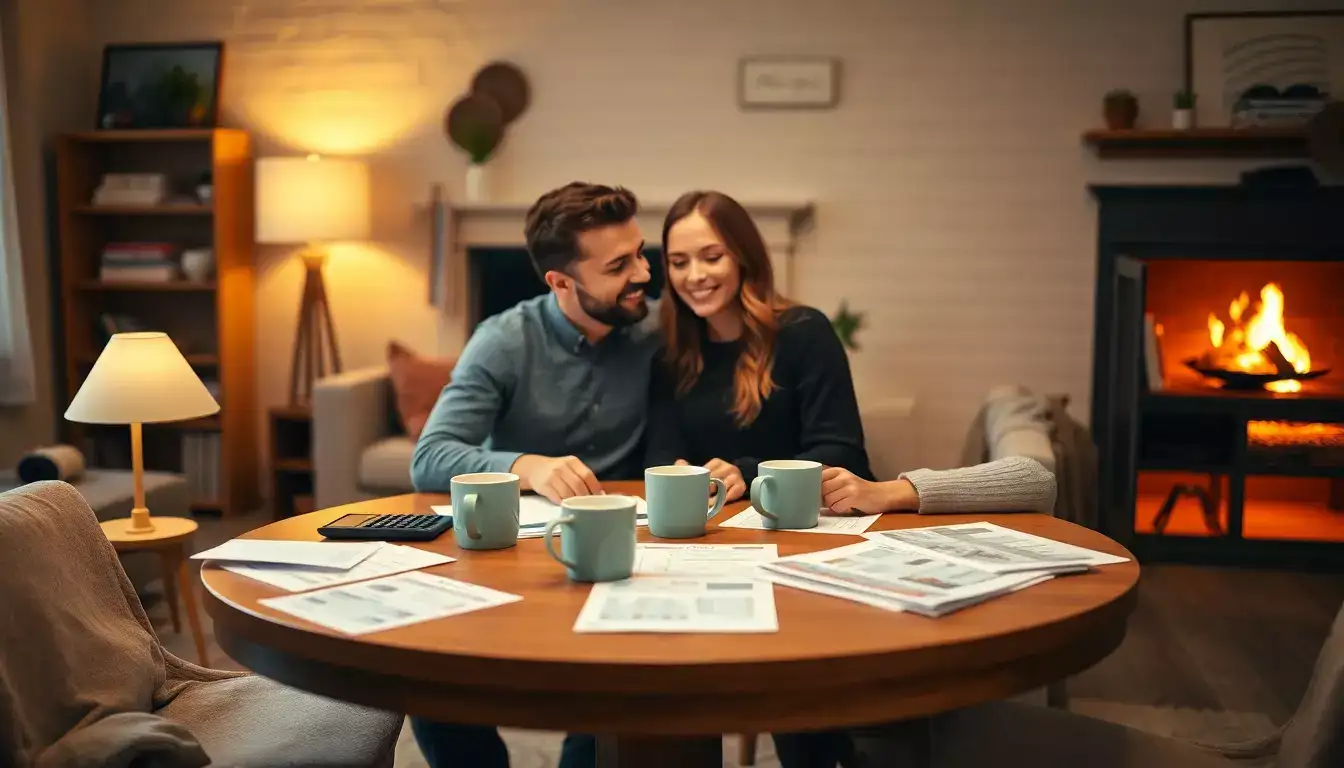
Start With Honest Money Talks
Open communication is the bedrock of a successful financial partnership. Sit down with your spouse to have a candid discussion about your individual financial habits, priorities, and challenges.
Key topics to cover
Create a Joint Budget
Once you’ve had your initial conversation, it’s time to plan how you’ll manage your day-to-day expenses together. A joint budget ensures transparency and helps track where your money goes.
Steps to build your budget
Choose a Bank Account Strategy
Deciding how to manage your bank accounts is an essential early step. Couples have multiple options:
Build an Emergency Fund Together
Life’s uncertainties can strain finances, making an emergency fund non-negotiable. Aim to save 3–6 months’ worth of essential living expenses in an easily accessible account.
Even starting small—₹5,000 to ₹10,000 per month—can gradually grow into a substantial safety net. Use this fund exclusively for unforeseen situations, such as medical emergencies or sudden job loss.
Align Your Financial Goals
Marriage is a partnership, and setting shared financial goals is part of building a life together. Identify both short-term and long-term goals to stay focused.
Examples of goals
Secure Adequate Insurance
Insurance is often overlooked but plays a crucial role in financial stability.
Handle Debts Strategically
Debt can quickly become a financial burden if not addressed properly. Develop a repayment plan to clear any existing loans or high-interest credit card balances.
Tips for managing debt
Save for Retirement Early
Even if retirement feels far away, starting early gives your savings more time to grow. Contribute to retirement schemes like the Employees’ Provident Fund (EPF), PPF, or National Pension System (NPS).
If both partners are earning, set aside at least 10–15% of your combined income for retirement. For better long-term returns, explore equity mutual funds through Systematic Investment Plans (SIPs).
Divide Financial Responsibilities
While managing finances as a team is essential, dividing responsibilities can make things more efficient. Play to each other’s strengths
Review Finances Periodically
Your financial priorities will evolve over time as your circumstances change. Make it a habit to review your budget, goals, and investments every six to twelve months.
Adjust your plans to reflect changes like promotions, family expansion, or new financial goals. Staying proactive ensures you’re always on track.
Building a strong financial foundation is a key aspect of a successful marriage. With open communication, clear goals, and a practical plan, managing money as a couple can be a rewarding journey. Start with small steps, stay transparent, and work together towards a financially secure and fulfilling future.
Start With Honest Money Talks
Open communication is the bedrock of a successful financial partnership. Sit down with your spouse to have a candid discussion about your individual financial habits, priorities, and challenges.
Key topics to cover
- Spending vs saving preferences.
- Existing debts, such as student loans or credit card balances.
- Shared financial goals, like buying a home or saving for children’s education.
Create a Joint Budget
Once you’ve had your initial conversation, it’s time to plan how you’ll manage your day-to-day expenses together. A joint budget ensures transparency and helps track where your money goes.
Steps to build your budget
- Monitor your combined spending for a month to identify patterns.
- Categorise expenses into essentials (rent, utilities, groceries) and discretionary (dining out, entertainment).
- Agree on spending limits for each category.
Choose a Bank Account Strategy
Deciding how to manage your bank accounts is an essential early step. Couples have multiple options:
- Joint account: Ideal for shared expenses like bills, rent, and groceries. Both can contribute a percentage of their income.
- Separate accounts: Maintain individual accounts for personal expenses while splitting shared costs.
- Hybrid approach: Combine both strategies by using a joint account for mutual expenses and personal accounts for individual spending.
Build an Emergency Fund Together
Life’s uncertainties can strain finances, making an emergency fund non-negotiable. Aim to save 3–6 months’ worth of essential living expenses in an easily accessible account.
Even starting small—₹5,000 to ₹10,000 per month—can gradually grow into a substantial safety net. Use this fund exclusively for unforeseen situations, such as medical emergencies or sudden job loss.
Align Your Financial Goals
Marriage is a partnership, and setting shared financial goals is part of building a life together. Identify both short-term and long-term goals to stay focused.
Examples of goals
- Short-term: Paying off credit card debt, saving for a vacation, or buying furniture.
- Long-term: Purchasing a home, saving for retirement, or building a college fund for future children.
Secure Adequate Insurance
Insurance is often overlooked but plays a crucial role in financial stability.
- Life insurance: If one spouse is the primary earner, ensure adequate coverage to protect the family’s financial future.
- Health insurance: Invest in a comprehensive plan, especially if your employer doesn’t provide family coverage.
Handle Debts Strategically
Debt can quickly become a financial burden if not addressed properly. Develop a repayment plan to clear any existing loans or high-interest credit card balances.
Tips for managing debt
- Prioritise high-interest debts first.
- Avoid new loans unless absolutely necessary.
- Consider consolidating debts for easier management.
You may also like
- Not just Rekha Gupta and Arvind Kejriwal: LK Advani, Manish Sisodia issued notices in Delhi SIR
- Uttarakhand CM Dhami joins women in traditional Chachani dance during Badrinath visit
- Delhi SIR: Advani, Sisodia figure in list of voters with 'discrepancies'
- Heavy Rainfall Expected in Several Districts of Telangana Until September 22, IMD Warns
- '27,000 votes, 27 seats': Akhilesh lays out Samajwadi Party strategy to counter BJP in UP polls
Save for Retirement Early
Even if retirement feels far away, starting early gives your savings more time to grow. Contribute to retirement schemes like the Employees’ Provident Fund (EPF), PPF, or National Pension System (NPS).
If both partners are earning, set aside at least 10–15% of your combined income for retirement. For better long-term returns, explore equity mutual funds through Systematic Investment Plans (SIPs).
Divide Financial Responsibilities
While managing finances as a team is essential, dividing responsibilities can make things more efficient. Play to each other’s strengths
- One partner can manage budgeting and bill payments.
- The other can handle investments and long-term financial planning.
Review Finances Periodically
Your financial priorities will evolve over time as your circumstances change. Make it a habit to review your budget, goals, and investments every six to twelve months.
Adjust your plans to reflect changes like promotions, family expansion, or new financial goals. Staying proactive ensures you’re always on track.
Building a strong financial foundation is a key aspect of a successful marriage. With open communication, clear goals, and a practical plan, managing money as a couple can be a rewarding journey. Start with small steps, stay transparent, and work together towards a financially secure and fulfilling future.
Loving Newspoint? Download the app now