8 Types Of Notices You May Receive Before Or After ITR Processing – Did You Get One?

Income tax notices can arrive at any stage of the tax filing process , whether before or after the Income Tax Return (ITR) is processed. Each notice serves a distinct purpose, addressing different discrepancies or issues. Understanding these notices is crucial to responding appropriately and avoiding further complications. Here's a breakdown of the common income tax notices you might receive if errors are detected in your ITR: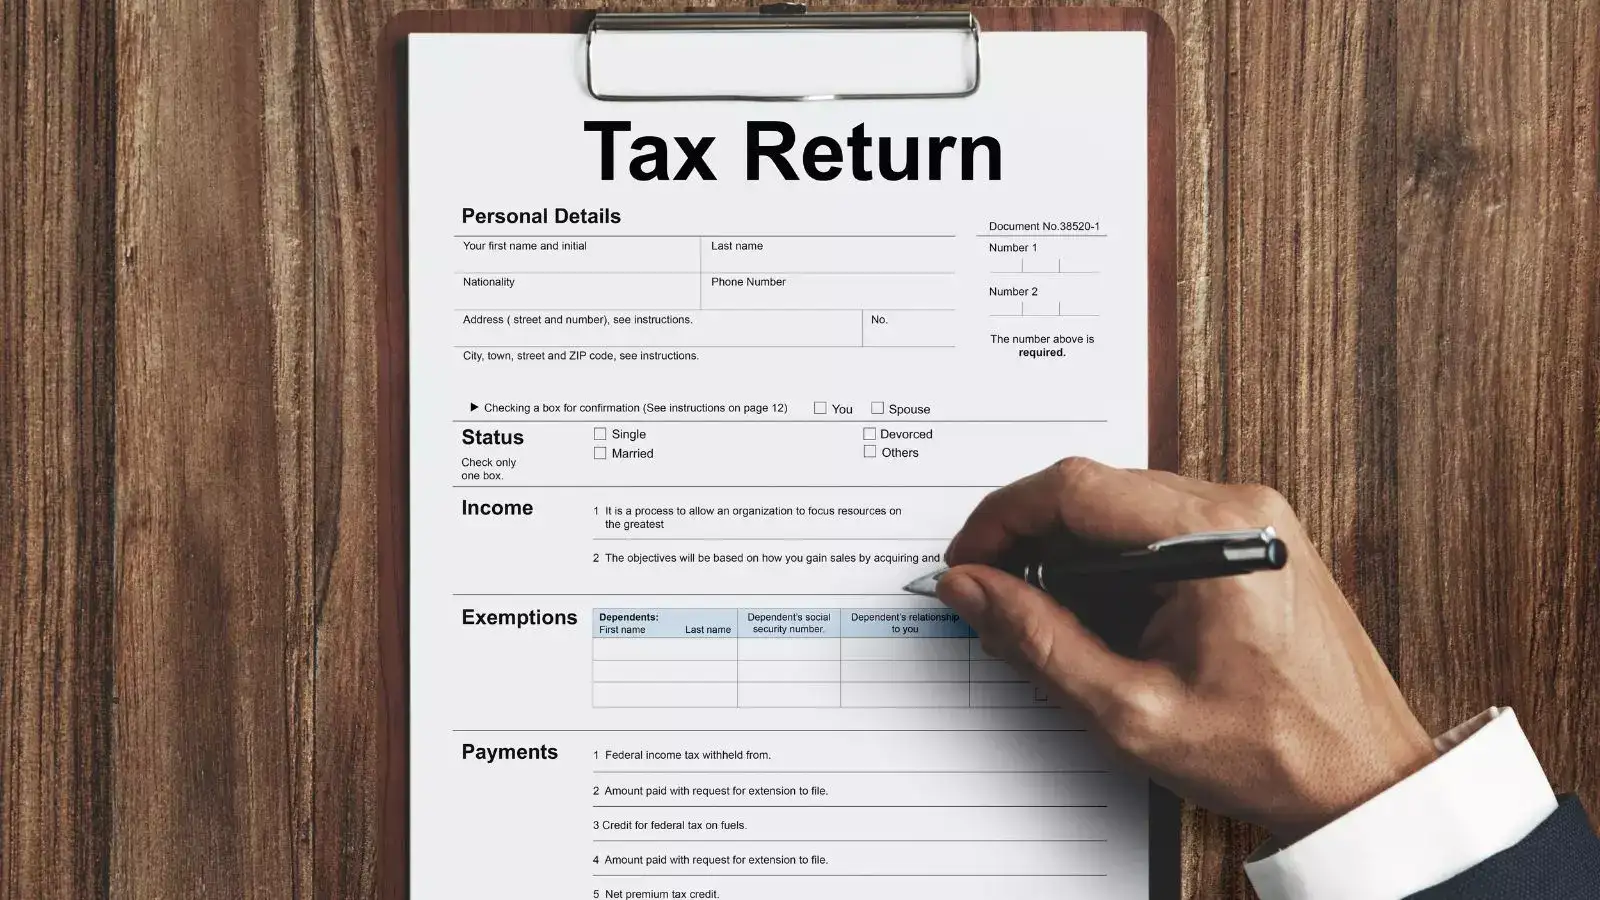
1. Section 143(1)(a) – Intimation Notice
This is known as an Intimation Notice and is sent once the Income Tax Department successfully processes the ITR filed by a taxpayer. The notice informs you if the tax calculations submitted by you match those computed by the tax department. If discrepancies arise between the ITR filed and the tax department’s calculations, the notice will explain the reasons behind the difference.
Possible Reasons:
This mismatch may result from calculation errors, incorrect claims, interest miscalculations under Sections 234A/B/C, or discrepancies between your ITR and Form 26AS.
Time to Respond:
You need to respond within 30 days if the notice highlights differences in your calculations. If no errors are found or the notice is regarding a refund, no response is necessary.
2. Section 139(9) – Defective Return Notice
This notice indicates that your ITR is considered defective, often due to incomplete or incorrect information provided during filing. Common errors include using the wrong ITR form or claiming exemptions like House Rent Allowance (HRA) without proper salary breakdowns.
Common Reasons:
Claiming HRA but lacking a corresponding HRA component in your salary.
Claiming TDS on income but failing to report the corresponding income, such as FD interest.
Time to Respond:
You must respond within 15 days of receiving the notice. If needed, you can request an extension.
3. Section 142(1) – Inquiry Before Assessment
Known as an inquiry notice, it is issued when no ITR has been filed despite evidence of income above the basic exemption limit. It requires you to submit a valid ITR and provide explanations for any discrepancies.
Possible Reasons:
Failure to file an ITR despite having taxable income.
Request for supporting documents to validate the claims in your filed ITR.
Time to Respond:
Typically, the time limit to respond is 15 days, but it can vary depending on the notice.
4. Section 143(2) – Scrutiny Assessment Notice
This notice is sent for a detailed assessment, often referred to as a "scrutiny." The tax department wants to verify the authenticity of the income, deductions, and other claims made in your ITR.
Possible Reasons:
A scrutiny assessment is done to check the genuineness of the various claims made in your ITR.
Time to Respond:
Generally, you have 15 days to respond. The specific time limit will be mentioned in the notice.
5. Section 148 – Income Escaping Assessment
This notice is issued if the tax department believes that certain income has escaped assessment in a previous year. Before reassessment, a show cause notice is sent under Section 148A(b) asking why the case should not be reassessed.
Time to Respond:
The taxpayer has 30 days to respond to the notice, either explaining or rectifying the escaped income.
Issuance Deadline:
For income up to Rs 50 lakh, notice can be issued within 3 years and 3 months of the assessment year.
For income exceeding Rs 50 lakh, reassessment can be done within 5 years and 3 months.
6. Section 245 – Refund Adjustment Against Previous Dues
This notice informs taxpayers that their current year’s tax refund will be adjusted against unpaid tax dues from previous years.
Possible Reasons:
Unpaid tax dues from a previous year could trigger this notice, allowing the department to offset the refund.
Time to Respond:
You have 30 days to respond, especially if you disagree with the dues or have already paid the tax.
7. Section 154 – Rectification of Errors
This notice is issued when the Income Tax Department identifies mistakes in the claims made in the ITR after it has been processed. The department issues the notice to correct these errors.
8. Section 263 – Revision of Erroneous Order
This notice is sent if the Commissioner of Income Tax finds that an order passed by an assessing officer was erroneous and harmful to the government’s interest. The notice can be issued within 12 months from the end of the year in which the erroneous order was passed.
Other Notices:
Section 131(1A): Issued if there is suspicion of income concealment.
Understanding the nature of each tax notice and responding within the stipulated time is essential to avoid penalties or further legal action. Always review your ITR carefully before filing to minimize the chances of receiving such notices.
1. Section 143(1)(a) – Intimation Notice
This is known as an Intimation Notice and is sent once the Income Tax Department successfully processes the ITR filed by a taxpayer. The notice informs you if the tax calculations submitted by you match those computed by the tax department. If discrepancies arise between the ITR filed and the tax department’s calculations, the notice will explain the reasons behind the difference.
Possible Reasons:
This mismatch may result from calculation errors, incorrect claims, interest miscalculations under Sections 234A/B/C, or discrepancies between your ITR and Form 26AS.
Time to Respond:
You need to respond within 30 days if the notice highlights differences in your calculations. If no errors are found or the notice is regarding a refund, no response is necessary.
2. Section 139(9) – Defective Return Notice
This notice indicates that your ITR is considered defective, often due to incomplete or incorrect information provided during filing. Common errors include using the wrong ITR form or claiming exemptions like House Rent Allowance (HRA) without proper salary breakdowns.
Common Reasons:
Claiming HRA but lacking a corresponding HRA component in your salary.
Claiming TDS on income but failing to report the corresponding income, such as FD interest.
Time to Respond:
You must respond within 15 days of receiving the notice. If needed, you can request an extension.
3. Section 142(1) – Inquiry Before Assessment
Known as an inquiry notice, it is issued when no ITR has been filed despite evidence of income above the basic exemption limit. It requires you to submit a valid ITR and provide explanations for any discrepancies.
Possible Reasons:
Failure to file an ITR despite having taxable income.
Request for supporting documents to validate the claims in your filed ITR.
Time to Respond:
Typically, the time limit to respond is 15 days, but it can vary depending on the notice.
4. Section 143(2) – Scrutiny Assessment Notice
This notice is sent for a detailed assessment, often referred to as a "scrutiny." The tax department wants to verify the authenticity of the income, deductions, and other claims made in your ITR.
Possible Reasons:
A scrutiny assessment is done to check the genuineness of the various claims made in your ITR.
Time to Respond:
Generally, you have 15 days to respond. The specific time limit will be mentioned in the notice.
5. Section 148 – Income Escaping Assessment
This notice is issued if the tax department believes that certain income has escaped assessment in a previous year. Before reassessment, a show cause notice is sent under Section 148A(b) asking why the case should not be reassessed.
You may also like
- 17-Year-Old Shot Dead in Manipur, Leaders Condemn Violence
- Gujarat Police Seizes ₹86.63 Lakh Worth of Liquor in Rajkot, Eight Arrested
- New Selfie and Viewpoints Enhance Char Dham Yatra Experience in Uttarkashi
- No median cuts, surface intersections on future high-speed NH corridors: NHAI
- Speeding SUV Strikes Pilgrims in Himatnagar, One Dead and Eleven Injured
Time to Respond:
The taxpayer has 30 days to respond to the notice, either explaining or rectifying the escaped income.
Issuance Deadline:
For income up to Rs 50 lakh, notice can be issued within 3 years and 3 months of the assessment year.
For income exceeding Rs 50 lakh, reassessment can be done within 5 years and 3 months.
6. Section 245 – Refund Adjustment Against Previous Dues
This notice informs taxpayers that their current year’s tax refund will be adjusted against unpaid tax dues from previous years.
Possible Reasons:
Unpaid tax dues from a previous year could trigger this notice, allowing the department to offset the refund.
Time to Respond:
You have 30 days to respond, especially if you disagree with the dues or have already paid the tax.
7. Section 154 – Rectification of Errors
This notice is issued when the Income Tax Department identifies mistakes in the claims made in the ITR after it has been processed. The department issues the notice to correct these errors.
8. Section 263 – Revision of Erroneous Order
This notice is sent if the Commissioner of Income Tax finds that an order passed by an assessing officer was erroneous and harmful to the government’s interest. The notice can be issued within 12 months from the end of the year in which the erroneous order was passed.
Other Notices:
Section 131(1A): Issued if there is suspicion of income concealment.
Understanding the nature of each tax notice and responding within the stipulated time is essential to avoid penalties or further legal action. Always review your ITR carefully before filing to minimize the chances of receiving such notices.
Loving Newspoint? Download the app now